

The Logan Group Securities, a Roseville, California-based brokerage and investment advisory firm, was censured and fined by FINRA in an accepted letter of Acceptance, Waiver, and Consent (AWC) dated July 27, 2026.
According to FINRA, the firm willfully failed to establish and enforce supervisory procedures designed to comply with Regulation Best Interest, failed to meet Form CRS requirements, and failed to reasonably supervise recommendations involving deferred variable annuities. The firm consented to the findings without admitting or denying them. Investors who received variable-annuity recommendations from The Logan Group Securities during the periods in question may want to understand what these findings mean for their accounts.
Investors who believe they received unsuitable or poorly supervised recommendations may benefit from reviewing their options for broker misconduct claims.
What Do Current Disclosures Report About The Logan Group Securities?
The Logan Group Securities (CRD# 40259) has at least 3 regulatory disclosures on record, according to its FINRA BrokerCheck report. Kevin Christopher Logan is listed as the sole proprietor and chief compliance officer. The firm has been a FINRA member since April 1996 and operates as a sole proprietorship with a single branch office in Roseville, California.
The most recent and most significant disclosure involves FINRA AWC case number 2021069397901, dated July 27, 2026. FINRA censured The Logan Group Securities, imposed a $70,000 fine, and required corrective measures, including certification that it implemented a supervisory system reasonably designed to address the identified deficiencies. According to FINRA’s September 2026 disciplinary report, the respondent is identified as Logan, Kevin Christopher doing business as The Logan Group Securities.
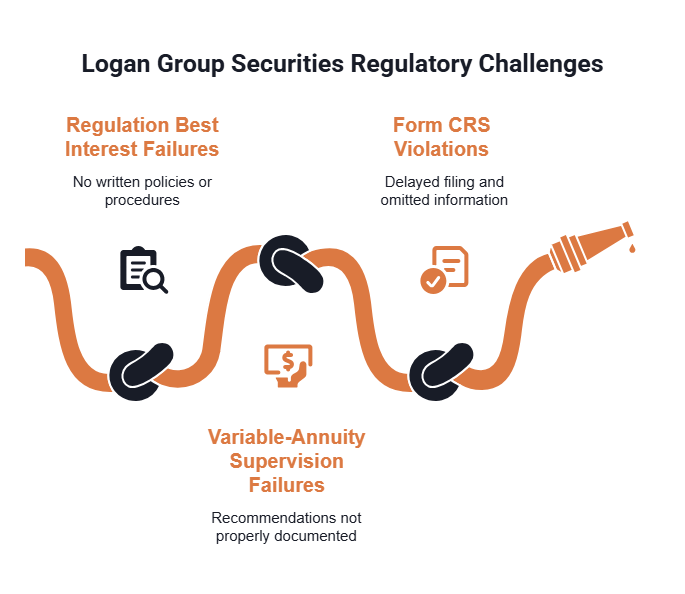
FINRA’s findings in the 2026 action address the following areas:
- Regulation Best Interest failures (FINRA Rules 3110, 2010, and Reg BI Compliance Obligation): From June 30, 2020, through the relevant period, the firm allegedly had no written policies or procedures addressing Regulation Best Interest. Between August 2021 and November 2021, its Reg BI procedures allegedly provided only general information and did not explain how to prevent, detect, or correct violations. The firm’s procedures were also found not reasonably designed to obtain and analyze sufficient customer information to establish a reasonable basis for recommendations to purchase or exchange variable annuities in the best interest of retail customers.
- Variable-annuity supervision failures (FINRA Rules 3110, 2330, and 2010): From March 2021 through the relevant period, the firm allegedly failed to reasonably supervise recommendations to purchase and exchange deferred variable annuities. Approximately one-third of variable-annuity purchase and exchange recommendations were not documented using the firm’s Client Account Form. When the forms were used, they allegedly lacked information about various deferred variable-annuity features, and the firm often did not otherwise disclose those features to customers.
- Form CRS violations (Exchange Act Section 17(a)(1) and Rule 17a-14): The firm was required to file Form CRS with the SEC by June 30, 2020, but did not file it until October 2020 and did not deliver it to retail investors until September 2021. FINRA found that the Form CRS omitted required information and stated that the firm and its personnel had no legal or disciplinary history, despite the firm’s existing disciplinary record. The firm did not update its Form CRS to disclose that history until July 14, 2023.

We Have Recovered Over
$350 Million for Our Clients Nationwide.
What Do Past Regulatory Actions Indicate for The Logan Group Securities Investors?
The 2026 FINRA action was not the first time The Logan Group Securities faced regulatory scrutiny. Two prior regulatory events are part of the firm’s record.
In an earlier FINRA AWC dated March 17, 2021 (case number 2018056455201), the firm was censured and fined $15,000 for inadequate written supervisory procedures related to multi-share-class variable-annuity recommendations. FINRA identified deficiencies involving L-share contracts, disclosure forms, expense-ratio documentation, investment objectives, and risk-tolerance information. The firm was involved in approximately $2.8 million in 24 L-share variable-annuity sales during the period covered by that matter.
Additionally, the California Department of Financial Protection and Innovation (DFPI) issued a consent order on March 14, 2023 addressing untimely Form ADV amendments and the firm’s failure to disclose the 2021 FINRA action for its advisory business. The California order required the firm to pay a $2,500 penalty, comply with a desist-and-refrain order, and file an amended Form ADV disclosure.
Taken together, these three regulatory events indicate supervisory and disclosure deficiencies across multiple years. The 2021 FINRA action addressed variable-annuity supervision procedures. The 2023 California order addressed late disclosure of the 2021 FINRA action. The 2026 FINRA action then found continued and broader failures in Regulation Best Interest compliance, variable-annuity supervision, and Form CRS delivery and accuracy. For investors who held accounts at The Logan Group Securities during these periods, the pattern raises questions about whether recommendations were adequately reviewed and whether they received the disclosures they were entitled to under federal and state securities rules.
“These types of violations typically turn on whether a firm had written procedures reasonably designed to address the specific risks in its business, whether recommendations were properly documented and reviewed, and whether required disclosures delivered accurately and on time. For affected customers, this can raise questions about whether the firm and its representatives met their disclosure and supervision obligations under FINRA rules governing broker conduct and account-related communications.”
–Donnell Much
How Meyer Wilson Werning Can Help
A FINRA fine is a regulatory sanction. It does not automatically compensate individual investors who may have suffered losses from unsuitable recommendations or inadequate disclosures. Whether an investor can recover losses depends on case-specific facts, including the recommendations made, the disclosures provided, account documentation, the investor’s financial situation, and any applicable arbitration agreement.
Meyer Wilson Werning represents investors nationwide in arbitration and securities claims. With more than 75 years of combined experience and over $350 million recovered for clients, the firm’s attorneys work with investors to evaluate whether their losses may be recoverable.
Investors who held accounts at The Logan Group Securities and received variable-annuity recommendations during the relevant periods should preserve their account statements, trade confirmations, Client Account Forms, correspondence, and product materials. Contact us today for a free and confidential consultation to discuss your options.
Our lawyers are nationwide leaders in investment fraud cases.
Frequently Asked Questions
What was The Logan Group Securities fined for?
FINRA censured and fined The Logan Group Securities $70,000 in an AWC dated July 27, 2026. FINRA found willful violations involving Regulation Best Interest policies and supervision, Form CRS requirements, and supervision of deferred variable-annuity purchases and exchanges. The firm consented to the findings without admitting or denying them.
Did the alleged conduct occur after Regulation Best Interest took effect?
Yes. The FINRA findings cover conduct beginning June 30, 2020, the date Regulation Best Interest became applicable to broker-dealers. According to FINRA, the firm initially had no written Reg BI policies and later adopted procedures that were too general to explain how to prevent, detect, or correct violations.
What did FINRA find about The Logan Group Securities’ Form CRS?
FINRA found that The Logan Group Securities filed Form CRS after the June 30, 2020 deadline, did not deliver it to retail investors until September 2021, omitted required information, and stated that the firm had no legal or disciplinary history despite its existing record. The firm updated the Form CRS to disclose that history on July 14, 2023.
Can an investor recover losses after a regulatory action against a broker-dealer?
A regulatory fine does not automatically compensate individual investors. Whether recovery is possible depends on case-specific facts, including the recommendations made, disclosures provided, account documents, losses sustained, and any available arbitration claim. Investors should preserve statements, trade records, account forms, communications, and product materials for a thorough review.
Recovering Losses Caused by Investment Misconduct.